23 Apr 2026
4 clever ways to support your adult children financially without compromising your retirement
It’s natural to want to help your children overcome challenges and move forwards in life, no matter how old they are.
Whether it’s clearing their debts or paying for a deposit on their first home, bolstering your children’s finances might seem like a good way to use your wealth. Indeed, IFA Magazine reports that 61% of parents of over-18s are financially supporting their children.
However, without careful planning, such generosity could disrupt your retirement plans and jeopardise your long-term financial security.
According to the research, 75% of parents financially supporting adult children say it has affected their financial situation; 27% have dipped into their savings, and 15% are planning to delay their retirement or have a more modest lifestyle as a result.
This doesn’t mean you can’t help your loved ones navigate the financial ups and downs of life. With a little forward planning, you could offer your children the help they need in a way that encourages them to become financially independent and protects your long-term plans.
Keep reading to discover four clever ways to support your adult children financially while keeping your retirement plans on track.
1. Seek professional advice to get a clear understanding of your finances
Before offering any money to your children, it’s essential to have a clear picture of your finances and how much support you can afford to give – without jeopardising your future security.
As a parent who’s eager to see their children happy, you might find that your emotions cloud your judgment. That’s why it’s crucial to speak to your financial planner before making any big decisions.
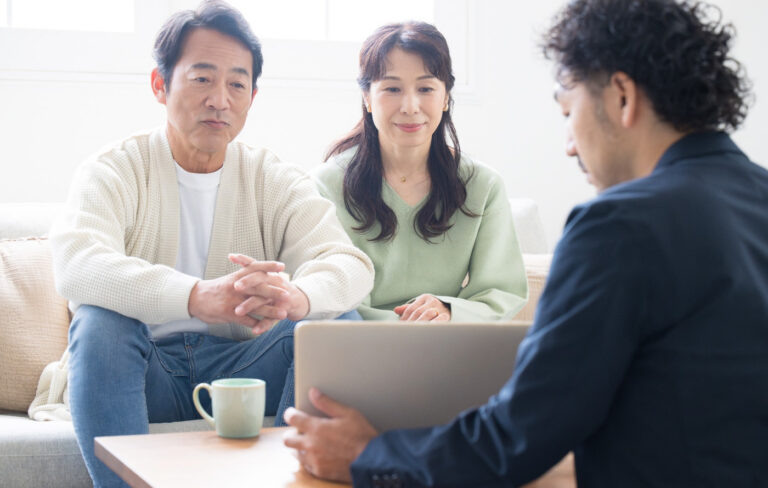
Your financial planner can provide an objective overview of your assets, income, liabilities and cash flow, to help you understand what level of help is sustainable. Using sophisticated cashflow modelling software, they can show you how affordable different gifting or lending scenarios might be in the short and long term.
Your financial planner will also make sure you consider key questions, such as ‘How much money do you need to maintain your desired retirement lifestyle?’ and ‘What are the potential tax implications of giving or lending money to your children?’
By crunching the numbers first, you can share your wealth with confidence, knowing that you’re not risking the retirement you’ve worked so hard to achieve.
2. Invite your children to share your home while they save
Rent or mortgage payments are likely to be one of the biggest expenses your adult children face. The Guardian recently revealed that UK housing costs have risen 41% in the five years between 2021 and 2026, for both renters and owners.
As such, providing a free or low-cost place to stay – rather than handing over cash – could be a great way to help your children achieve their financial goals without dipping into your own funds.
For example, you could let them stay rent-free while they attend university to minimise the amount of debt they build up. Alternatively, you might choose to invite older children to return home and pay a peppercorn rent while they build up a house deposit.
3. Offer your time and financial knowledge
There are plenty of ways to help your children improve their financial situation that won’t cost you a penny from your retirement fund.
Many young adults face big financial decisions, such as when and how to buy their first property and how to manage debt effectively. This could feel overwhelming and your children may be unsure about which path to choose.
By sharing the skills and knowledge you’ve learned over the years, such as effective budgeting and long-term planning, you could help them develop positive money habits and avoid common pitfalls.
Offering your time and knowledge in these ways could be a powerful strategy for building your adult children’s financial confidence and resilience. Giving them the tools to make sound, independent decisions about their money may be just as valuable as handing over a cheque in the long term.
You might also want to consider inviting them to a meeting with your financial planner, so they can see wealth management in action and ask a professional any questions they have.
4. Use annual allowances to gift inheritance during your lifetime
If you’ve already factored an inheritance for your children into your long-term financial plan, consider gifting some of this wealth during your lifetime. This could allow you to help your children when they need it most – for example, if they’re starting a family or setting up a business – without compromising your retirement lifestyle. What’s more, you’ll have the joy of seeing your family enjoy their inheritance.
Making gifts can also be a tax-efficient way to pass on your wealth.
Each tax year, you’re entitled to several allowances and exemptions that allow you to pass on gifts without incurring inheritance tax (IHT). For example, in 2026/27, you can give away up to £3,000 without it counting towards the value of your estate for IHT purposes. Larger gifts may also be exempt if you survive for seven years after giving them.
The rules around IHT are complex, so it’s worth scheduling a meeting with your financial planner to discuss your options and develop a gifting strategy that works for you.
Please note
This article is for general information only and does not constitute advice. The information is aimed at retail clients only.
All information is correct at the time of writing and is subject to change in the future.
Please do not act based on anything you might read in this article. All contents are based on our understanding of HMRC legislation, which is subject to change.
The Financial Conduct Authority does not regulate estate planning, cashflow planning, or tax planning.